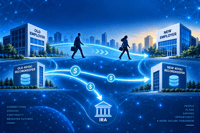
 The retirement industry appears to be reaching an important consensus: the rollover process must become more automated, more interoperable, and less dependent on participant action. Recent responses to IRS Notice 2026-49 reinforced a theme that has been building for years across the defined contribution marketplace. Participants change jobs more frequently than ever, retirement accounts become fragmented, and too many Americans cash out or lose track of retirement savings as they move through the workforce.
The encouraging news is that a growing number of industry stakeholders recognize that solving these challenges requires a more coordinated infrastructure approach. Whether commenters described it as a clearinghouse, an electronic platform, an interoperability network, or an ACATS-style utility, the direction was consistent. The retirement system needs better connectivity between institutions and a more efficient way to move savings to where participants can continue building long-term retirement security.
For Retirement Clearinghouse (RCH), that’s an important validation of a philosophy that has guided our work for nearly two decades.
An Industry Converging Around a Common Principle
The most striking aspect of the Notice 2026-49 comment record is not disagreement over the need for modernization. Rather, it is the broad recognition that retirement rollovers should be processed through standardized, technology-enabled infrastructure that reduces friction for participants and institutions alike.
Across the responses, several themes emerged:
- Greater automation of rollover transactions
- More direct institution-to-institution communication
- Standardized data exchange and recordkeeping
- Reduced paperwork and manual processing
- Fewer opportunities for participant savings leakage
- Improved plan-to-plan portability as workers change employers
These objectives closely mirror the foundational principles behind auto portability and the broader clearinghouse vision that RCH has long advocated.
The debate is increasingly shifting from whether a retirement savings portability network is needed to what kind of network can most effectively serve the retirement ecosystem.
Retirement Is Different from Brokerage
Some commenters understandably point toward existing financial-market infrastructure, particularly ACATS-style transfer systems, as a potential model for retirement rollovers.
There is value in learning from successful transfer frameworks. However, retirement savings portability presents challenges that extend beyond simply transferring assets from one account to another.
Retirement transactions frequently involve unique considerations, including:
- No unitary “account” structure, as in banking or brokerage
- Qualification and eligibility requirements
- Plan-specific rules and restrictions
- Participant identification and matching
- Coordinated movement of money and participant data
- Roth and pre-tax asset distinctions
- Beneficiary information
- Outstanding loan considerations
- Fiduciary and ERISA-related obligations
A retirement-focused clearinghouse must support the complex operational, compliance, and participant protection requirements that are unique to the retirement system.
Why Experience Matters
As industry discussions increasingly focus on utility models and interoperability frameworks, it is important to recognize a critical distinction between theoretical infrastructure and operational infrastructure.
Building a retirement savings portability network requires more than technology. It requires:
- Proven matching methodologies
- Established relationships with recordkeepers
- Operational workflows capable of handling complex retirement transactions
- Regulatory experience
- Demonstrated success in reducing cashout leakage
The retirement industry has spent years discussing how portability should work. RCH has spent years operating portability solutions at scale, as clearly evidenced by the Portability Services Network, an industry-owned and governed utility.
That distinction is significant. The challenges associated with locating accounts, validating participant data, coordinating multiple institutions, and moving assets & data efficiently and securely are not hypothetical. They are operational realities that demand tested solutions.
Neutrality, Industry Governance and Regulatory Oversight
For an interoperability framework to succeed in a fragmented environment, market participants must have confidence that the infrastructure operates neutrally and supports the interests of the broader system rather than any single institution. That has long been a defining characteristic of RCH’s approach.
One commenter expressed an explicit preference for an NSCC/regulated utility over “private entities such as Retirement Clearinghouse.”
That framing does not accurately describe the model being advanced by RCH. One only needs to consider PSN, which is not a proprietary platform controlled for the benefit of a single commercial provider; it is an industry-owned and governed utility formed by the retirement industry's largest recordkeepers to facilitate auto portability and preserve small-balance retirement savings.
Moreover, PSN operates within the highly regulated ERISA framework and is subject to oversight and regulatory guidance promulgated by the U.S. Department of Labor.
Therefore, the real policy question is not whether retirement savings portability should be supported by a regulated utility, but whether the industry should build upon an existing retirement-specific utility with demonstrated operating experience or attempt to repurpose securities-transfer infrastructure designed to solve fundamentally different problems.
The Economics Favor a “Many-to-Many” Connections Model
As other commenters suggested, direct API connections between institutions can improve communication and facilitate transactions.
The challenge is scalability. A marketplace composed of hundreds of retirement providers creates a complex web of potential bilateral integrations. Every new connection introduces additional implementation, maintenance, governance, and security requirements.
A clearinghouse model simplifies that challenge. Rather than requiring every provider to connect individually with every other provider, participants can connect through a common network that establishes consistent standards and shared protocols. This “many-to-many” approach has proven effective in numerous areas of financial services because it lowers costs, accelerates adoption, and increases interoperability.
The Goal Is Better Participant Outcomes
Ultimately, infrastructure discussions should never lose sight of the people the retirement system exists to serve.
Millions of workers leave retirement assets behind every year as they change jobs. Small balances are particularly vulnerable to cashout leakage and loss. Account fragmentation can make retirement planning more difficult and reduce participants' ability to accumulate meaningful long-term savings.
The objective is straightforward: create a retirement system in which savings can more easily follow workers throughout their careers, when they consent. Achieving that objective requires automation, interoperability, collaboration among institutions, and infrastructure designed specifically for retirement savers.
Looking Ahead
The growing support for clearinghouse-based solutions reflected in the Notice 2026-49 comment process is an encouraging sign that the industry is moving in that direction. As policymakers and industry stakeholders continue discussing the future of retirement savings portability, RCH believes the conversation should focus not only on what infrastructure is needed, but also on what infrastructure has already demonstrated its ability to advance participant outcomes.
The future of retirement savings portability will be built on connectivity, standardization and trust – and there is a working model that embodies those attributes now.